Quick Answer
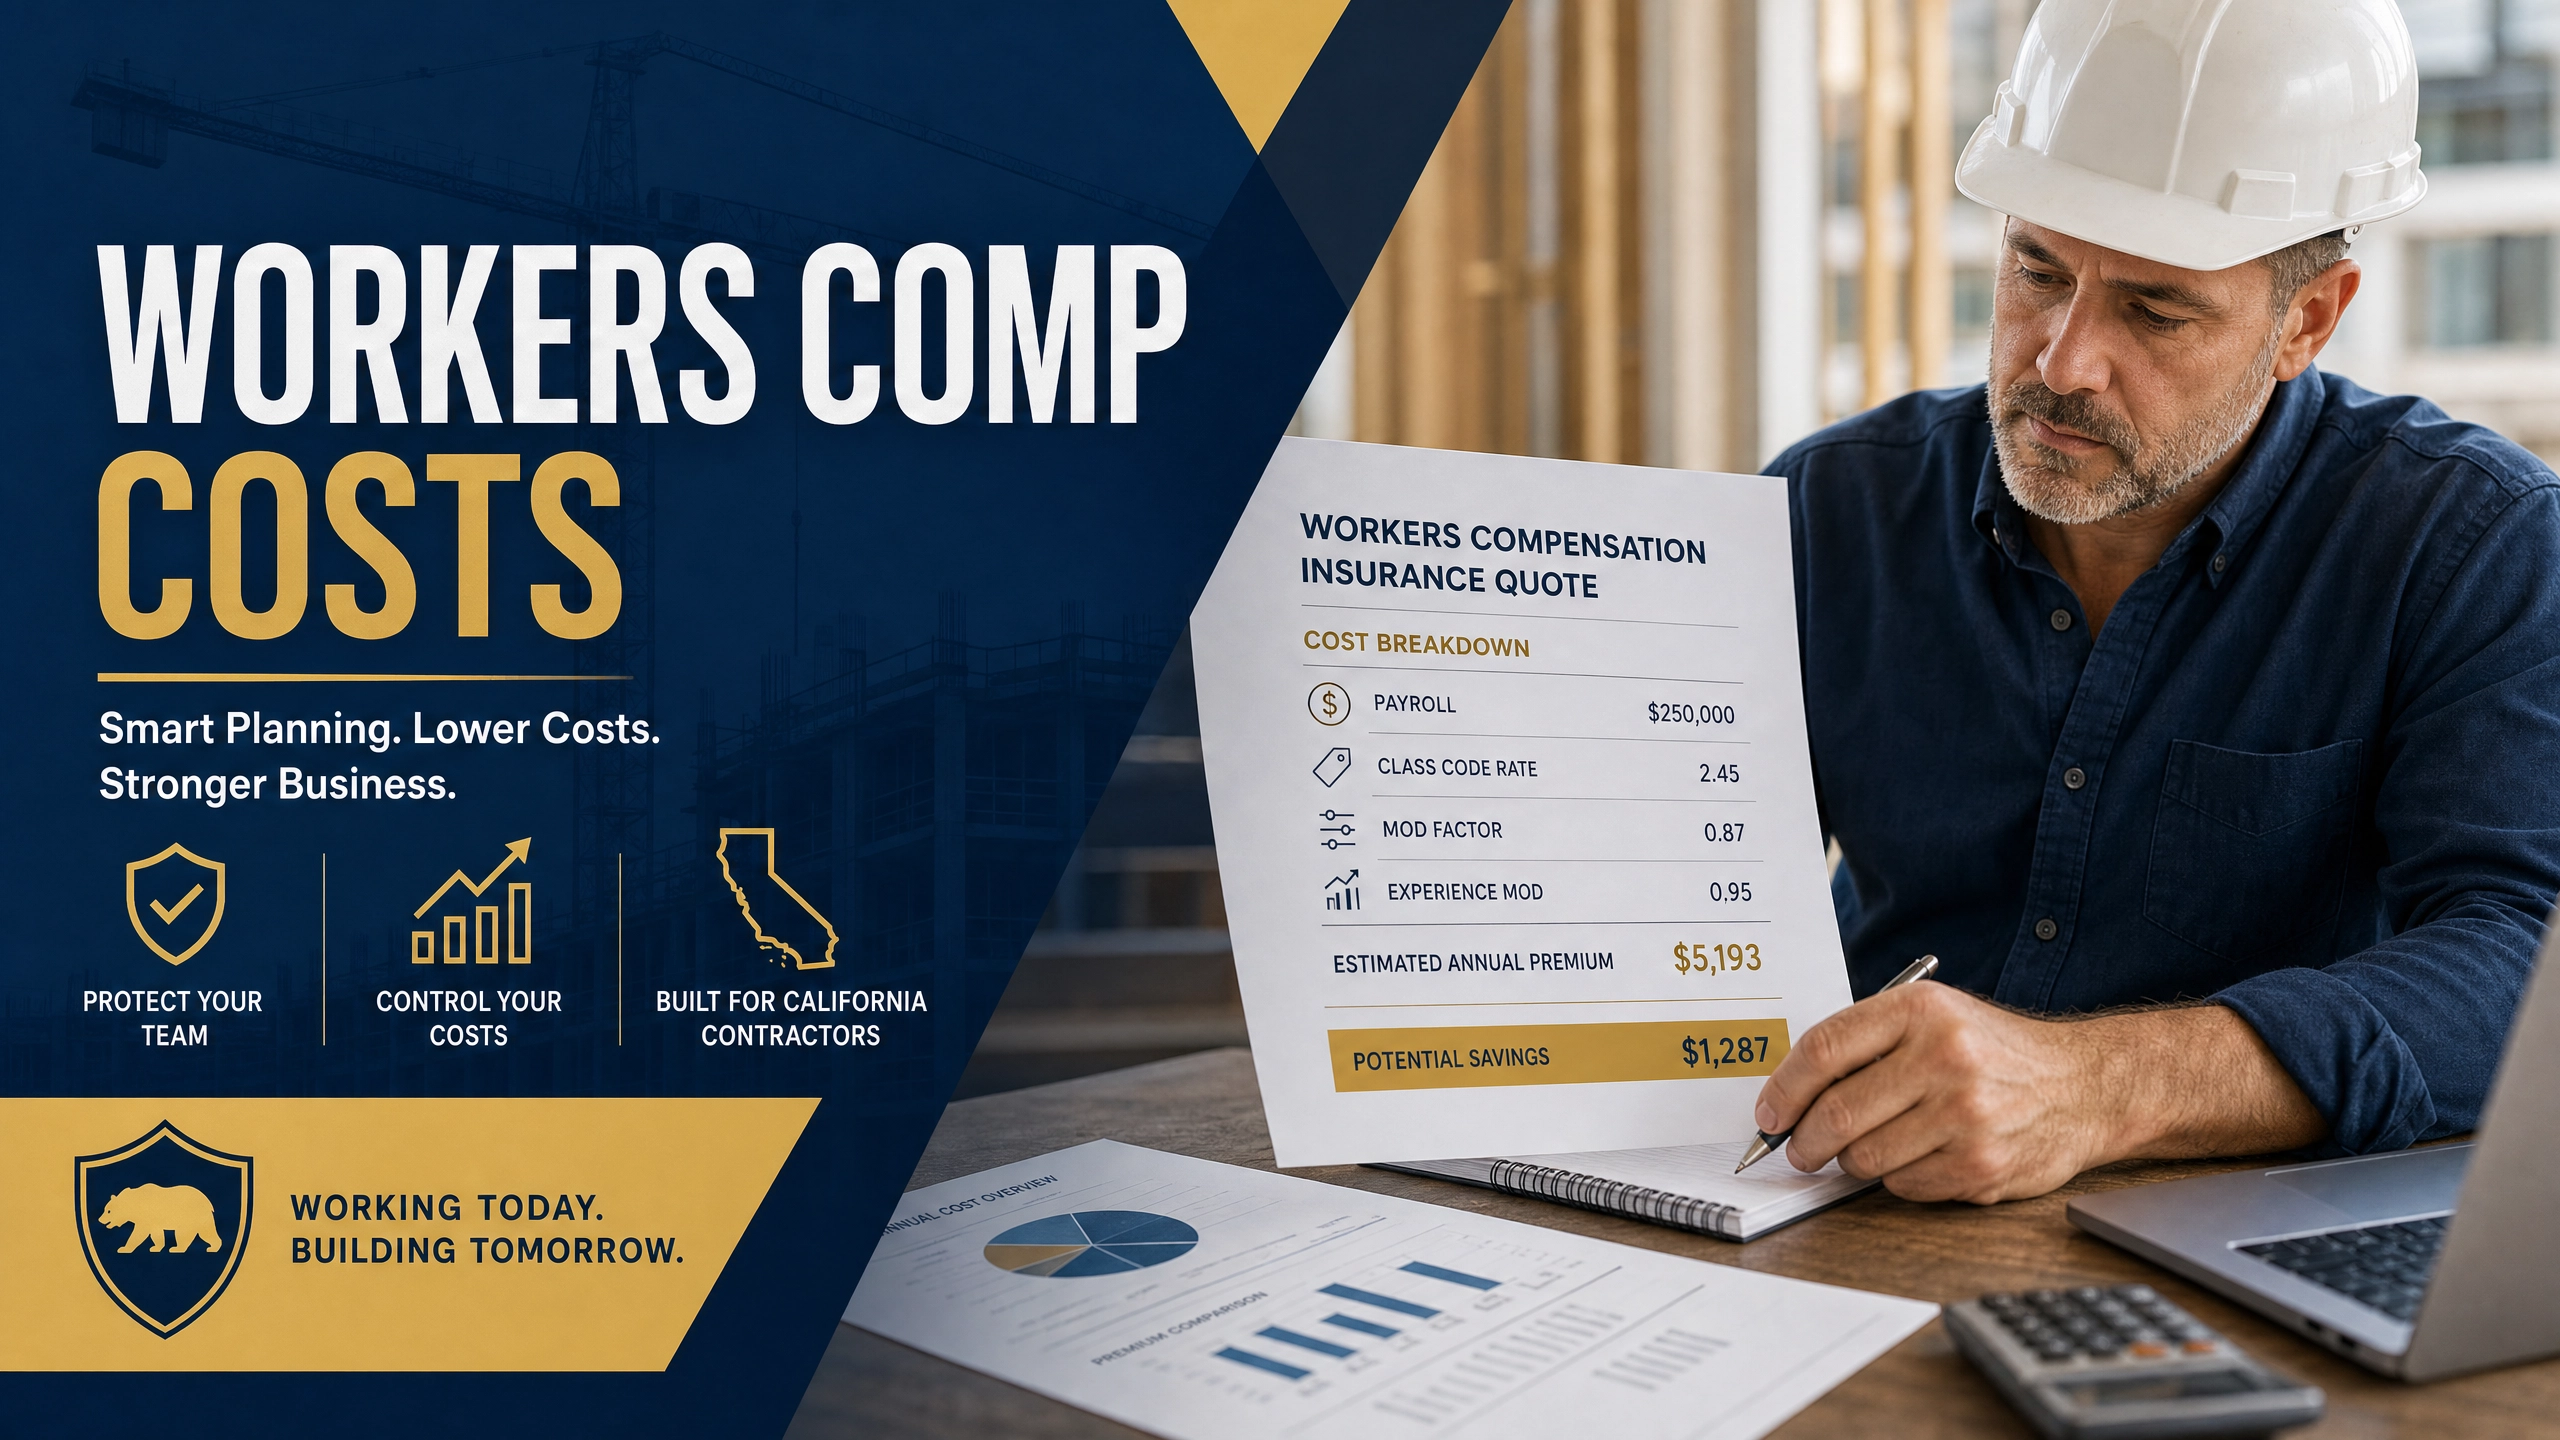
Workers' comp for a California contractor in 2026 typically runs from $800/year for a solo ghost policy to $30,000+/year for a 10-person roofing crew. The math is simple: your premium equals your annual payroll, divided by 100, multiplied by your WCIRB class code rate, then adjusted by your Experience Modifier (X-Mod). Roofers (Classes 5552/5553) pay the highest rates in California — pricing varies by classification, payroll, operations, claims history, limits, deductibles, and underwriting per $100 of payroll. Painters and landscapers pay much less. Call us at (858) 925-9555 with your CSLB license number and we'll come back with a real quote, not an estimate.
Table of Contents
- How California workers' comp is priced
- WCIRB class code rates by trade (2026)
- What your X-Mod actually does
- Real cost examples by crew size
- How to lower your premium
- Pay-as-you-go vs annual deposit
- Frequently Asked Questions
How California Workers' Comp Is Priced
Three numbers determine your annual workers' comp premium in California:
- Your WCIRB classification code — assigned to your trade by the Workers' Compensation Insurance Rating Bureau of California. Each class code has a base rate published in WCIRB advisory pure premium rate filings.
- Your annual payroll — total W-2 wages plus, in most cases, the value of 1099 subcontractor payments where the sub couldn't prove their own coverage.
- Your Experience Modifier (X-Mod) — a multiplier based on your three-year claims history vs the industry average for your class.
The formula:
(Annual payroll ÷ 100) × class rate × X-Mod = base premium
Carriers then add taxes, fees, and adjustments. The final number can vary 20–30% between carriers for the exact same risk — which is why we shop the market every renewal.
WCIRB Class Code Rates by Trade — California 2026
| Trade | WCIRB class | Typical rate per $100 payroll (2026) |
|---|---|---|
| Clerical / office staff | 8810 | pricing varies by classification, payroll, operations, claims history, limits, and underwriting |
| Painters (residential) | 5474 | pricing varies by classification, payroll, operations, claims history, limits, and underwriting |
| Electricians | 5190 | pricing varies by classification, payroll, operations, claims history, limits, and underwriting |
| Plumbing | 5183 | pricing varies by classification, payroll, operations, claims history, limits, and underwriting |
| HVAC / refrigeration | 5537 | pricing varies by classification, payroll, operations, claims history, limits, and underwriting |
| Carpentry — residential framing | 5403/5432 | pricing varies by classification, payroll, operations, claims history, limits, and underwriting |
| Landscape contractors | 0042 | pricing varies by classification, payroll, operations, claims history, limits, and underwriting |
| Concrete contractors | 5213 | pricing varies by classification, payroll, operations, claims history, limits, and underwriting |
| Excavation & dump truck | 6217 | pricing varies by classification, payroll, operations, claims history, limits, and underwriting |
| Drywall installation | 5445 | pricing varies by classification, payroll, operations, claims history, limits, and underwriting |
| Roofing — residential | 5552/5553 | pricing varies by classification, payroll, operations, claims history, limits, and underwriting |
| Roofing — commercial | 5552/5553 | pricing varies by classification, payroll, operations, claims history, limits, and underwriting |
Estimates only — based on 2026 WCIRB advisory pure premium rates and California carrier filings. Actual rate depends on your specific class assignment, experience modifier, claims history, and carrier. Sources: wcirb.com, California Department of Insurance carrier filings at insurance.ca.gov.
What Your X-Mod Actually Does
The Experience Modifier is the single biggest lever on your premium after class code. A 1.00 X-Mod is the industry average for your class. Below 1.00 is a discount. Above 1.00 is a surcharge.
Example: A California plumbing company with $400,000 in annual payroll at the Class 5183 mid-range rate of $6.75 per $100 has a base premium of $27,000. At a 0.85 X-Mod, the premium drops to $22,950. At a 1.20 X-Mod, it climbs to $32,400. Same payroll. Same trade. A 9,450-dollar swing on one number.
Your X-Mod is calculated by the WCIRB using three years of paid claims data — typically your prior 1st through 3rd policy years, dropping the most recent one. Once you understand how the math works, lowering your X-Mod becomes one of the highest-leverage moves you can make on your operating cost.
We do free X-Mod audits for our California contractor clients every renewal cycle.
Think your X-Mod is too high? Call (858) 925-9555 — we'll run the math against your three-year claims and tell you exactly what's driving your rate.
Real Cost Examples by Crew Size
| Scenario | Trade | Payroll | Approx. annual WC |
|---|---|---|---|
| Solo sole prop, no employees (ghost policy) | C-36 Plumbing | $0 | pricing varies by classification, payroll, operations, claims history, limits, and underwriting |
| 2-employee crew | C-10 Electrical | $120,000 | pricing varies by classification, payroll, operations, claims history, limits, and underwriting |
| 4-employee crew | C-20 HVAC | $240,000 | pricing varies by classification, payroll, operations, claims history, limits, and underwriting |
| 5-employee crew | C-33 Painting | $250,000 | pricing varies by classification, payroll, operations, claims history, limits, and underwriting |
| 6-employee crew | C-39 Roofing (residential) | $360,000 | pricing varies by classification, payroll, operations, claims history, limits, and underwriting |
| 10-employee GC mix | Class B (carpentry/supv) | $700,000 | pricing varies by classification, payroll, operations, claims history, limits, and underwriting |
Estimates only — based on 2026 advisory rate ranges and a 1.00 X-Mod. Real quotes vary by carrier, experience, claims, and additional coverages bundled with the WC.
How to Lower Your Premium
The biggest moves in order of impact:
- Lower your X-Mod. Maintain a clean three-year claims history. Avoid letting small claims drift into open status. Push for prompt claims closure.
- Separate your payroll by class code. If your office staff and field crew sit in one bucket, you're overpaying. Properly split, clerical payroll runs at the 8810 rate (around $0.30 per $100) instead of your field rate.
- Use a pay-as-you-go carrier. Avoid the year-end audit surprise; pay only on the payroll you actually run.
- Officer exclusions for corporations. If you hold your license as an LLC or corp and you're an active officer, the WCIRB Officer Exclusion form removes your wages from the rated payroll.
- Shop the market every renewal. Carrier appetites shift. The carrier that was most cost-effective for your class last year may be 20% higher this year.
Pay-As-You-Go vs Annual Deposit
Traditional WC works like this: the carrier estimates your annual payroll at binding, you pay a deposit, then they audit you at year-end and bill or refund the difference. Bad year-end audits are the #1 surprise expense for California contractors.
Pay-as-you-go integrates with your payroll system. Each pay period the carrier pulls actual payroll and bills the premium that week. No audit surprises, no big deposit, and cash flow matches the work you're actually doing. availability depends on the carrier, payroll arrangement, and underwriting.
If you run weekly payroll or your headcount fluctuates seasonally, pay-as-you-go almost always makes more sense.
Get a real workers' comp quote for your California operation after complete information, carrier processing, and underwriting. Call (858) 925-9555 or request a coverage review. We shop every carrier we're appointed with and tell you exactly what each one will cost.
Related Reading: - SB 216 Workers' Comp Ghost Policy Guide - CSLB Insurance Requirements - General Liability vs Workers' Comp - Workers' Compensation Insurance - Insurance for Roofers